
New AD/CVD Petitions Filed: Corrugated Pizza Boxes from China, Malaysia, and Türkiye
Background
On September 9, 2026, the American Pizza Boxes Manufacturers Coalition — comprising U.S. producers Smurfit Westrock plc and Pratt Industries, Inc. — together with the United Steel, Paper and Forestry, Rubber, Manufacturing, Energy, Allied Industrial and Service Workers International Union (USW), filed petitions with the U.S. Department of Commerce (DOC) and the U.S. International Trade Commission (ITC) seeking the imposition of antidumping (AD) duties on corrugated pizza boxes from the People's Republic of China, Malaysia, and the Republic of Türkiye, and countervailing (CVD) duties on such merchandise from Türkiye. Petitioners are represented by Wiley Rein LLP.
The petitions allege that subject imports increased 130% by quantity from 2023 to 2025 — from 40.2 million pounds to 92.4 million pounds under HTSUS 4819.10.0020 — and a further 46% between the first half of 2025 and the first half of 2026. By landed duty-paid value, imports from the three countries rose from $33.2 million in 2023 to $68.3 million in 2025. Petitioners allege that these imports have materially injured, and threaten further material injury to, the domestic industry.
Imports of corrugated pizza boxes from China classified under HTSUS 4819.10.00 are already subject to 25% Section 301 duties, and entries under that subheading from all three countries are covered by the Section 301 forced labor tariff action published in July 2026. The new AD/CVD duties, if imposed, would apply in addition to those measures and to any generally applicable tariffs.
Product Scope
Merchandise Covered
The merchandise covered by these investigations is certain corrugated food service boxes, commonly referred to as pizza boxes — boxes or cartons manufactured from paper, paperboard, and/or cardboard for use in the food service industry, including to hold pizza pies. The scope covers corrugated cardboard die-cut blanks, whether finished or unfinished and assembled or unassembled, including blanks shipped flat in ready-to-assemble bundles.
Covered boxes are produced from corrugated (fluted) cardboard sheets made from recycled or virgin paper or paperboard, bleached or unbleached, containing at least two outer layers with an inside fluted layer. The scope covers B-flute, C-flute, D-flute, and E-flute designs, as well as any equivalent types of corrugation or fluting. Country of origin is determined by where the corrugated cardboard sheet is produced.
Subject merchandise is covered regardless of shape (rectangular, square, round, hexagonal, octagonal, or otherwise). A finished, assembled subject box has a length of at least five inches, a width of at least five inches, and a height no greater than four inches; there is no maximum length or width. Boxes are covered with or without color or printing, coatings or linings (including grease-resistant treatments), ventilation holes or perforations, and features for holding condiments or other foods. The addition of non-paper materials such as liners, inserts, or holders does not remove merchandise from the scope.
Significantly for supply chain planning, the scope expressly covers boxes subjected to further processing in a third country — including printing, coating, trimming, cutting, punching, assembling, folding, or perforating — where such processing would not otherwise remove the merchandise from the scope if performed in the country of manufacture.
Merchandise Excluded
The scope language contains no express exclusions.
HTS Classifications
Subject merchandise is typically classified under HTSUS subheading 4819.10.0020 (sanitary food and beverage containers of corrugated paper or paperboard). The HTSUS subheading is provided for convenience and customs purposes only; the written description of the merchandise is dispositive.
Estimated Dumping and Subsidy Margins
Petitioners allege the following dumping margins, calculated on an ad valorem basis:
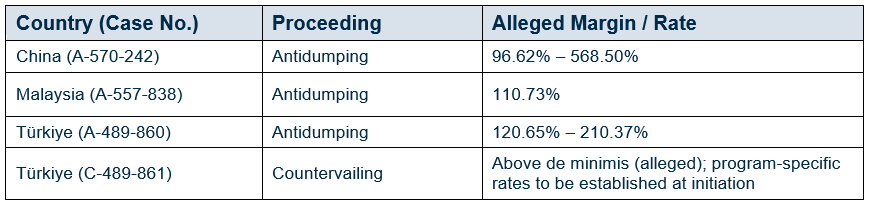
China is treated as a non-market economy, with normal value constructed using surrogate country data. The Türkiye subsidy allegations are set out in Volume V of the petitions; DOC will identify the programs it will investigate in its initiation notice.
Estimated Investigation Schedule
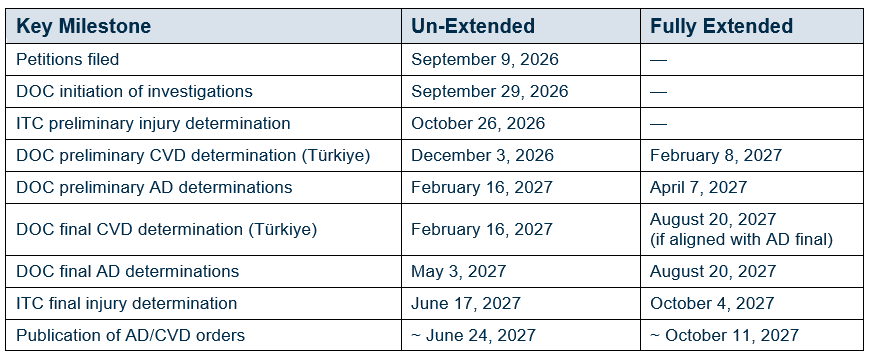
The following key milestones are estimated based on statutory deadlines running from the September 9, 2026 filing date, adjusted to the next business day where applicable. Actual dates will be set by Federal Register publication and may shift by several days.
Suspension of Liquidation and Retroactive Duties
Upon an affirmative preliminary determination, DOC will direct U.S. Customs and Border Protection to suspend liquidation of entries of subject merchandise and to require cash deposits of estimated duties at the preliminary rates. Absent extensions, suspension of liquidation and cash deposit requirements could begin as early as December 2026 for the Türkiye CVD investigation and February 2027 for the AD investigations.
Importers should be aware of critical circumstances exposure. If petitioners allege — and DOC and the ITC find — critical circumstances, suspension of liquidation applies retroactively to unliquidated entries made up to 90 days before the preliminary determination. Based on the un-extended schedule, the earliest date from which entries could be subject to retroactive suspension of liquidation is approximately September 4, 2026 for the Türkiye CVD investigation (90 days prior to the December 3, 2026 preliminary determination) and approximately November 18, 2026 for the AD investigations (90 days prior to the February 16, 2027 preliminary determinations). In practical terms, merchandise entering the United States now may already fall within the potential retroactive window on the CVD side, and entries from mid-November 2026 onward may be exposed on the AD side.
Final duty liability is established only upon publication of AD/CVD orders following affirmative final determinations by DOC and the ITC, with cash deposit rates subject to change at each phase of the proceedings.
Disclaimer
This alert is provided for general informational purposes only and is based on the public versions of the petitions as filed. It does not constitute legal, tax, or investment advice, and it should not be relied upon as such. Companies that import, purchase, produce, or export merchandise potentially within the scope of these investigations should assess their exposure and participation strategy promptly, as key deadlines — including ITC questionnaire responses and DOC quantity-and-value submissions — arise within weeks of filing.


